OneMain Financial

Screenshots
Details
- Rating
- 3.33K reviews
- Version
- 10.30.0
- Developer
- OneMain Financial
Analysis by Norviv
Managing a personal loan from a phone sounds simple, but the small details matter when a payment date is approaching or several people share the same household device. After spending time with OneMain Financial, I found it most useful as a focused finance app for customers who already have a OneMain account and want a more convenient way to stay on top of it. It is free to install, aimed at Everyone, and developed by OneMain Financial.
The app’s purpose is narrower than a full banking platform. I would not open it expecting everyday spending tools, a complete household budget, or a replacement for a general-purpose banking app. Its value comes from putting loan management, payment activity, and credit tracking in one mobile space. That focus makes it easier to understand, although it also means its usefulness depends heavily on whether you already use OneMain’s lending services.
How OneMain Financial fits into a shared household routine
When a household shares bills but keeps personal borrowing separate, I find it helpful to agree on a simple routine: the borrower checks the loan account, while everyone else coordinates only the money or reminders they have agreed to handle. That keeps the task visible without turning private account access into a shared responsibility. The next section looks at how to keep that arrangement practical when the phone itself is shared.
A practical scenario for couples and housemates
Imagine a household where one person handles rent and utilities while another is responsible for a personal loan. The person making the loan payment can use the app to check the account and keep the task separate from the rest of the household’s banking. That separation is helpful because it avoids mixing loan information into a shared checking-account workflow.
In my view, the most realistic use is a quick check before payday: open the app, review the loan information, confirm what needs attention, and then make the payment through the available account tools. A partner or housemate may remind the account holder about the date, but the person whose name is on the loan should remain the person making account decisions. The app can support coordination; it should not turn a private financial account into a communal one.
This distinction is especially important on a shared phone or tablet. A household might use one device for many services, but loan details are not ordinary household notes. I would treat the app as belonging to the borrower, even if everyone shares the hardware. That means avoiding casual handoffs while the account is open and making sure the device is returned to a normal locked state afterward.
What I would do before handing over the phone
OneMain Financial is designed around account access, so I would not leave it open for another person to browse. Before sharing the device, I would finish the session, close the app, and use the device’s normal screen-lock habits. I would also avoid saving account-related information in a shared notes app or sending screenshots through a family group chat.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This is not a criticism of the app so much as a reminder about context. A finance app can be perfectly convenient while still requiring more care than a recipe or weather app. The account boundary belongs to the borrower, and household convenience should not override that boundary.
For couples managing money together, a useful routine is to agree on who checks the loan, who provides funds for the payment, and who confirms that the task is complete. That arrangement prevents two common problems: both people assuming the other handled it, or both people trying to manage the same account without a clear plan. The app gives the account holder a direct place to check progress, while the household conversation handles the shared responsibility.
Setup is simple in concept, but identity matters
The first question I would ask before installing is not whether the app is free. It is whether I am an existing OneMain customer who needs mobile access to a loan account. If the answer is no, the app is unlikely to offer much practical value. Its role is account management, not general financial discovery.
During setup, I would use the borrower’s own account details and keep the login separate from other household members’ credentials. That sounds obvious, but shared devices often encourage shortcuts. Using one person’s saved details for another person’s account can create confusion later, especially when several financial apps are installed side by side.
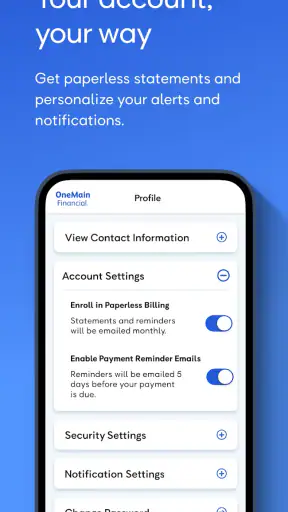
I also recommend deciding in advance where notifications, reminders, or account prompts should be seen. On a shared device, a message preview may reveal more than the owner intended. I would review the phone’s notification display and choose a level of visibility that matches the household’s privacy expectations. The exact controls available can depend on the device, so this is a broader phone-setting consideration rather than a promise about a special family mode inside the app.
The current release is version 10.30.0, and the app supports Android from version 7.0 onward. That makes it approachable for people using older compatible Android hardware, but I would still keep the operating system and device security current where possible. A finance app should not be the reason to ignore basic phone maintenance.
Coordinating payments without losing the account boundary
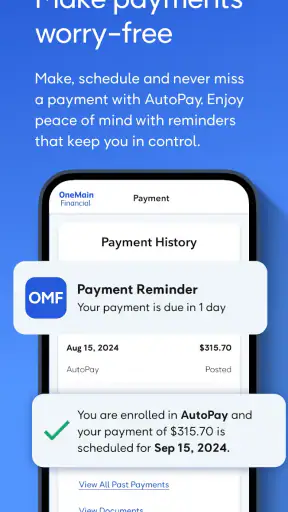
One of the app’s strongest everyday uses is reducing uncertainty around loan payments. Instead of relying only on a paper statement, a calendar note, or a conversation with a partner, the account holder can check the loan directly. That is valuable when household money moves between accounts at different times.
For example, one person might transfer money into a shared account while the borrower remains responsible for making the payment. I would use the app to verify the loan side of the process, then use the household’s agreed method for confirming that funds are available. Keeping those two steps distinct makes troubleshooting easier if something goes wrong.
A good habit is to check the account before making a payment rather than assuming the amount or timing has stayed the same. Loan obligations deserve a deliberate review, especially after a change in household income or a large unexpected expense. The app is useful here because it puts the relevant account information closer at hand, but it does not replace reading carefully and checking the source of the funds.
I would also avoid making a payment simply because another person says it is due. The borrower should open the account and verify the details personally. That small step protects against misunderstandings and keeps the final decision with the person legally responsible for the loan.
Credit tracking is helpful, but it needs context
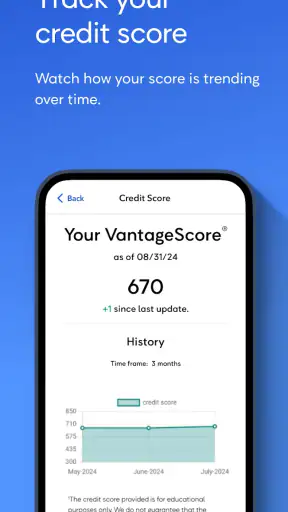
The credit-tracking element gives the app a broader purpose than payment processing alone. I like the idea of checking credit information in the same place where I review a loan, because it connects borrowing behavior with the wider picture. Still, I would treat any credit view as a monitoring aid rather than a complete financial diagnosis.
Credit information can change for reasons that are not immediately obvious, and a single view should not be used to make a major borrowing decision without further thought. If I were discussing the app with a partner, I would explain that seeing credit information is different from having control over another person’s credit profile. Each adult should decide what to share and when.
This matters in households where one person is more financially experienced than another. A helpful partner can explain what they are seeing, but should not pressure the account holder to reveal private details. The app can support an informed conversation; trust still depends on consent and respectful boundaries.
Age, trust, and the Everyone rating
The Everyone content rating makes the app broadly suitable from a storefront perspective, but that should not be confused with independent financial responsibility. A younger person may be able to encounter the app without objectionable content, yet loan management remains an adult financial task in most real household situations.
I would not give a child access to an adult borrower’s open account just because the app carries an Everyone rating. The important issue here is not entertainment content; it is privacy, identity, and the consequences of changing financial information. If a teenager is learning about credit, I would demonstrate general concepts without handing over live account access.
For older relatives who are less comfortable with smartphones, the app may be useful if a trusted person helps with navigation. I would keep the account holder present and let them make the final decisions. Assistance with finding a payment screen is very different from taking over the account or storing someone else’s login details.
Where it beats a general banking app
Compared with a general banking app, OneMain Financial has a clear advantage for a borrower who wants the loan itself kept separate from everyday spending. A banking app may show the outgoing payment, but it is not necessarily the best place to review the loan account or credit-related information. Having a dedicated destination can make the task easier to remember and easier to explain.
Compared with a mobile browser, the app feels more purposeful for repeated use. A browser can be flexible, especially on a shared computer, but a dedicated app reduces the temptation to search for the right page every time. I find that useful for short checks, provided the device belongs to the account holder or is handled carefully.
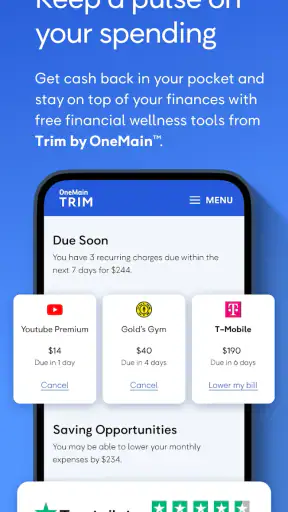
On the other hand, a general finance app may be better for someone whose main goal is budgeting across several banks, tracking household categories, or viewing investments. OneMain Financial is not the right choice for that broader job. Its focused design is a strength for loan customers and a limitation for anyone seeking an all-in-one financial dashboard.
Small points that affect the daily experience
The app’s free price removes one barrier to trying it, but free access should not be mistaken for free borrowing. The important financial terms belong to the loan agreement, not to the download itself. I would use the app to manage an existing relationship, not as a reason to take on credit without comparing the full cost and repayment responsibilities.
The app has built a substantial user base, with over a million installs and a 4.7 average from around twenty-eight thousand ratings. Those figures suggest that many people find the mobile experience useful, but they do not guarantee that every account situation will feel identical. Finance apps can be judged not only by their interface, but also by how well they fit a person’s particular loan and payment routine.
There are around three thousand three hundred written reviews, which gives prospective users more material to consider than a single short summary. I would still read recent comments critically and separate interface complaints from questions about loan terms or account decisions. An app can be easy to use even when a customer dislikes the financial product itself, and the reverse can also happen.
One non-obvious trade-off is that convenience can encourage overchecking. Opening the app repeatedly may feel reassuring, but it does not improve a household budget by itself. I would create a simple rhythm: check when planning the payment, review after completing it, and return when a genuine question arises. That keeps the app useful without turning it into a source of unnecessary worry.
Who should use it, and who should skip it
I would recommend OneMain Financial to an existing OneMain borrower who wants mobile access to loan management, payment activity, and credit tracking. It is particularly suitable for someone who prefers a focused app rather than searching through a broad banking platform. It also works well for households that want a clear division of responsibility: one borrower manages the account, while others coordinate around the payment without sharing credentials.
I would skip it if I do not have a OneMain account, because the central features are tied to that relationship. I would also choose a broader personal-finance tool if my priority were household budgeting across multiple institutions. Someone who dislikes managing financial information on a phone may prefer a browser or another established method, especially if the device is shared and privacy is difficult to maintain.
People considering a new loan should not judge the borrowing decision by the app alone. A convenient interface is useful after choosing a product, but it does not determine whether the loan fits the household’s income, emergency savings, or long-term plans. I would compare the financial terms separately and use the app as the management layer, not the deciding factor.
My household verdict
After using it as a focused finance companion, I see OneMain Financial as a practical tool rather than a complete money-management system. Its best quality is clarity: the borrower has a dedicated place to manage a OneMain loan, make payments, and follow credit-related information without blending everything into a general banking dashboard.
The main friction comes from the same focus. People outside the OneMain customer base will find little reason to keep it installed, and households must take privacy seriously when devices or responsibilities are shared. The app helps with coordination, but it cannot decide who should have access, who supplies the money, or whether a loan is affordable.
For an existing borrower who wants a free mobile way to stay organized, I think it is worth using. I would install it on the account holder’s device when possible, keep login boundaries clear, check payment details deliberately, and treat credit tracking as information rather than a verdict. Used that way, it becomes a sensible part of a household routine without pretending to replace careful financial judgment.
Frequently Asked Questions
01What is OneMain Financial, and what services does it offer?
OneMain Financial is a lending and financial-services app that allows eligible users to explore personal loan options, review account information, make payments, and manage their applications from a mobile device. Depending on eligibility and location, users may receive offers for secured or unsecured personal loans. Loan amounts, rates, terms, and available features vary, so reviewing the full agreement is important before accepting an offer.
02Can I apply for a personal loan through the OneMain Financial app?
Yes, the app can help eligible customers begin or manage a personal-loan application, although some steps may require additional verification through the website, by phone, or at a branch. Applicants should expect to provide personal, employment, income, and financial information. Approval is not guaranteed, and the final offer may include an origination fee, interest rate, repayment term, and payment amount based on the applicant’s circumstances.
03Does using OneMain Financial affect my credit score?
Checking whether you may qualify or viewing potential loan information may involve a soft credit inquiry in some situations, which generally does not affect your credit score. However, submitting a formal application or accepting a loan can result in a hard inquiry, depending on the process and product. Making payments on time may support your credit history, while missed payments can negatively affect it.
04Is the OneMain Financial app safe to use?
The official OneMain Financial app is designed to provide secure access to account and loan-management features, including authentication and protected transmission of information. Users should download it only from the official Google Play Store or Apple App Store, verify the publisher name, keep the app updated, and avoid sharing passwords or verification codes. No financial app can eliminate every security risk, so device protection remains essential.
05What should I check before accepting a OneMain Financial loan?
Before accepting an offer, carefully review the annual percentage rate, interest rate, loan amount, repayment schedule, total repayment cost, monthly payment, origination or other fees, and whether collateral is required. Make sure the payment fits comfortably within your budget and understand the consequences of late or missed payments. Comparing the offer with alternatives from banks, credit unions, or other lenders can also help you make an informed decision.


